African Airlines Lead Passenger Growth but Struggle to Fill Expanding Capacity
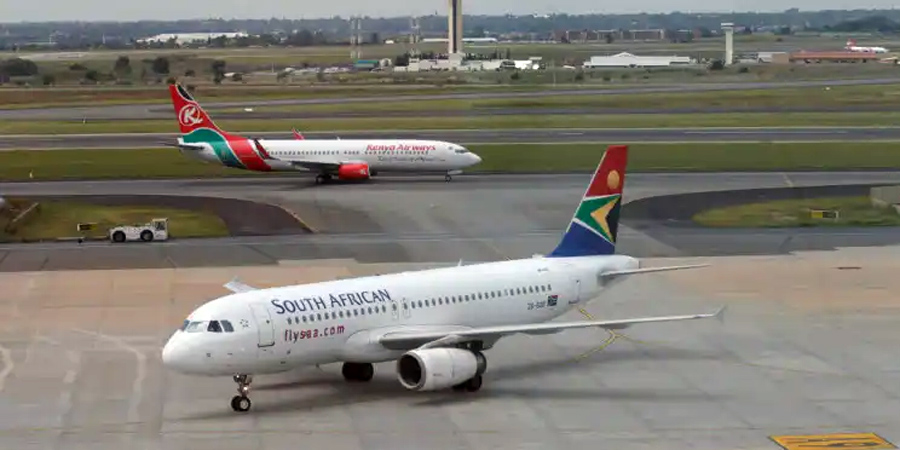
African airlines recorded the strongest overall passenger traffic growth among global regions in September, but capacity expansion outpaced demand, pushing the regional load factor to 73.5pc, the lowest worldwide.
African airlines recorded the strongest overall passenger traffic growth among global regions in September, but the expansion came at the cost of declining aircraft occupancy as airlines added capacity faster than demand increased.
Data released by the International Air Transport Association (IATA) show that passenger demand across African carriers’ domestic and international networks grew by 5pc year-on-year, while available seat capacity expanded by 7.7pc.
The imbalance pushed the average passenger load factor down by 1.9 percentage points to 73.5pc, the lowest among the world’s regions.
The figures illustrate the challenge facing African airlines as they expand networks and increase frequencies in anticipation of growing demand in a market where air travel remains relatively underdeveloped but operational costs and commercial pressures remain high.
Africa accounted for just 2.2pc of global passenger traffic in September, underlining the limited scale of its aviation market despite its population of more than 1.5 billion people and the growth opportunities associated with expanding regional trade, tourism and business travel.
The picture was somewhat stronger in international operations, where African airlines recorded an 8pc increase in passenger demand compared with September 2025. Capacity grew by 8.8pc, however, leaving the international passenger load factor 0.6 percentage points lower at 74.8pc.
Although international traffic growth suggests sustained demand for connections between African markets and destinations beyond the continent, the relatively low occupancy levels indicate that airlines still have considerable work to do in converting network expansion into stronger seat utilisation.
The passenger load factor measures the proportion of available seat capacity occupied by paying passengers. A falling load factor does not automatically translate into losses, since airline profitability also depends on fares, cargo revenues, operating costs and the mix of passengers carried. However, sustained declines can put pressure on revenue performance, particularly where capacity additions are not matched by sufficient demand.
Africa’s performance contrasted with a weaker global passenger market. Worldwide demand fell by 0.5pc in September, while capacity contracted by 0.2pc, leaving the global load factor down 0.3 percentage points at 83.2pc.
The Middle East was the principal drag on international traffic, with airlines in the region recording a 7.5pc decline in international demand and a 3.3pc reduction in capacity. Their passenger load factor fell by 3.6 percentage points to 78.3pc.
North American carriers also faced weak international demand, which remained flat year-on-year, while European airlines recorded growth of 1.8pc.
Latin American airlines posted the strongest international demand growth, at 8.2pc, supported by capacity expansion of 7.6pc. Their international load factor improved by 0.5 percentage points to 83.9pc.
For African carriers, the September figures present a more complicated picture than the headline growth ranking suggests. Stronger passenger demand is encouraging, but the faster pace of capacity expansion points to the need for airlines to match fleet deployment and route development more closely with the growth of their markets.
In its assessment of the September figures, IATA said the global market remained affected by geopolitical uncertainty and volatile fuel prices, although most international markets showed some improvement compared with August.
Marie Owens Thomsen, IATA’s Senior Vice President Sustainability and Chief Economist, said the 0.5pc decline in global passenger demand reflected weakness in the Middle East and North America.
She noted that global scheduled seat capacity was expected to remain above 2025 levels in October and November, although growth remained weak and uneven across regions.
Related Posts
 Uganda Airlines Expands its West-African Footprint with Direct Service to Accra
 Airlines Spent USD 24.5bn Processing Payments in 2025, IATA Says
 Uganda Returnees Look to Rebuild Livelihoods as Government Pledges UGX2bn
 ERAM Award puts Uganda’s Animal-Health Manufacturing Ambitions in Focus
 Why Community-Led Climate Action Is Essential to Building Climate Resilience
 Agroecology Week Targets Stronger links Between Farmers, Policy and Markets
Get business news delivered to you everyday
Latest News

African Airlines Lead Passenger Growth but Struggle to Fill Expanding Capacity

Shift to Value sees Equity Bank Bancassurance Premiums Rise to UGX16.13bn

Uganda Airlines Expands its West-African Footprint with Direct Service to Accra

Airlines Spent USD 24.5bn Processing Payments in 2025, IATA Says

Uganda Returnees Look to Rebuild Livelihoods as Government Pledges UGX2bn

Beyond Gold Exports, Uganda’s Next Test Is Economic Transformation

ERAM Award puts Uganda’s Animal-Health Manufacturing Ambitions in Focus

Why Community-Led Climate Action Is Essential to Building Climate Resilience

Stanbic Commits UGX20m to Virunga Gorilla Marathon’s Conservation Drive

Energy Ministry and Equity Bank target lower hotel energy costs through green investment initiative