Mastercard Targets Africa’s Costly Cross-border Payment Bottlenecks with Single-use Virtual Travel Card
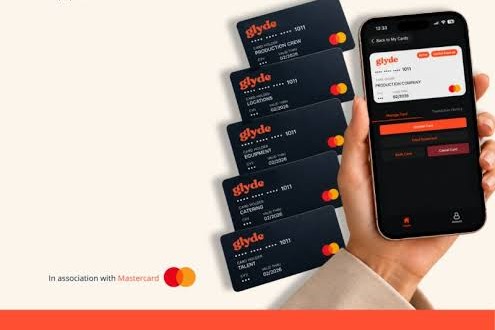
Mastercard has partnered with South Africa’s Glyde Payments to introduce single-use virtual cards for travel businesses across Southern Africa, targeting costly cross-border payment inefficiencies and expanding the role of digital payment infrastructure in African commerce.
Mastercard’s latest move into Africa’s travel payments market highlights the growing commercial importance of the financial infrastructure connecting businesses across borders, as payment networks and fintech providers seek to capture value from the continent’s expanding digital economy.
Through a partnership with South African fintech Glyde Payments, Mastercard is introducing single-use virtual cards for travel businesses across Southern Africa, marking the region’s first issuance under its Mastercard Wholesale Program.
The arrangement is designed to address inefficiencies in the travel industry’s payment chain, where hotel bookings and other transactions often involve multiple suppliers, intermediaries and currencies. Delayed settlements, difficult reconciliation processes and exposure to fraud can increase operating costs and constrain cash flow.
Under the arrangement, each booking receives a unique virtual card number, with spending controls tied to specified merchants, transaction amounts and validity periods. This allows businesses to manage individual payments more closely while reducing the risks associated with conventional payment arrangements.
According to London-based news and market intelligence platform Allen Dreyfus, the development is significant not merely because it promises faster transactions, but because it highlights the growing importance of control over the payment infrastructure connecting African businesses to global commerce.
The opportunity also extends beyond tourism. Greater payment transparency and automation could improve cash-flow management, reduce operational risks and create new opportunities for fintech companies developing services for businesses operating across Africa’s fragmented markets.
For Mastercard, the initiative strengthens its position in business-to-business payments, an area where digital payment solutions can become embedded in the everyday transactions between suppliers, service providers and commercial intermediaries.
However, the wider adoption of such technologies will depend on their ability to navigate persistent structural challenges, including currency restrictions, differing regulatory frameworks and uneven digital infrastructure across African markets.
Dreyfus argues that the central question is whether local fintech companies will capture a meaningful share of the value generated by these innovations, or whether international payment networks will retain much of the commercial advantage from controlling the underlying infrastructure.
The partnership therefore points to a broader contest over the future of Africa’s digital payments ecosystem, where the ability to facilitate transactions efficiently could become as commercially important as the goods and services being exchanged.
Related Posts
 AU pushes Climate-smart Irrigation to Deliver Kampala Agenda Ambitions
 Ugandan Designers Earn Continental Recognition at Addis Fashion and Leather Fair
 Nile Breweries Invests UGX4bn in Sebei Barley Handling Facility as Local Sourcing Expands
 Isaiah Rwanyekiro: Wearing my Scars with Pride After Years of Battling Cancer
 Equity Bank Unveils Richard Byarugaba as it Targets Ugandans in Kenya with Cross-border Investment Proposition
 SITA’s New eWAS+ Electronic Flight Bag Integrates Weather and Flight Operations Data for Pilots
Get business news delivered to you everyday
Latest News

AU pushes Climate-smart Irrigation to Deliver Kampala Agenda Ambitions

Mastercard Targets Africa’s Costly Cross-border Payment Bottlenecks with Single-use Virtual Travel Card

Ugandan Designers Earn Continental Recognition at Addis Fashion and Leather Fair

Nile Breweries Invests UGX4bn in Sebei Barley Handling Facility as Local Sourcing Expands

Equity Bank Extends Women’s Enterprise Financing Programme to Buvuma Island

Isaiah Rwanyekiro: Wearing my Scars with Pride After Years of Battling Cancer

Equity Bank Unveils Richard Byarugaba as it Targets Ugandans in Kenya with Cross-border Investment Proposition

United Opens new Dulles Concourse as it Expands International Network

ICEA LION Urges Stronger Employee Protection as Insurer Backs HR Conference with UGX15m

Stanbic Alerts Customers to Tighter OTC Transaction Limits Ahead of January 2027 Changes