Another month of mixed fortunes for Africa’s airlines as passenger demand soars amidst cargo dip in May
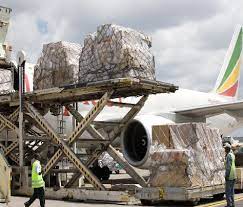
African airlines posted robust performance in the global air passenger market in May 2025, recording the highest year-on-year growth across all regions. However, the buoyant passenger numbers stood in sharp contrast to a decline in the region’s air cargo demand, underlining persistent challenges in trade and logistics.
According to the latest data released by the International Air Transport Association (IATA), passenger demand on the continent rose by 9.5pc compared to May 2024, outpacing the global growth rate of 5.0pc. That growth came off a 6.2pc increase in capacity by African carriers, while the passenger load factor – a measure of how much available seating was sold – reached 74.9pc, up 2.2 percentage points over the same period last year but 8.5pc below the global average.
That performance positioned Africa as a standout performer among global regions, despite contributing a relatively modest 2.2pc to the world’s total revenue passenger kilometers (RPKs). Notably, the Africa-Asia corridor was the fastest-growing international route in May, with a 15.9pc year-on-year expansion – a signal of deepening connectivity and emerging demand along South-South trade lanes.
Globally, international air travel demand rose by 6.7pc, while domestic travel increased by 2.1pc. Overall, the industry recorded a load factor of 83.4pc, slightly below May 2024’s levels. IATA Director General Willie Walsh attributed the uneven global growth to geopolitical tensions and shifting travel patterns, particularly the slowdown in North American markets.
“Africa’s passenger growth performance is impressive,” Walsh said. “But the disparity between passenger and cargo trends in some regions, including Africa, reflects broader economic headwinds and the shifting nature of global trade.”
Indeed, on the cargo front, African carriers saw a 2.1pc year-on-year dip in demand in May. This downturn came despite a 2.7pc increase in available cargo capacity, resulting in a subdued cargo load factor of 42.2pc – below the global average of 44.5pc.
Globally, air cargo demand in May rose by 2.2pc, supported by stable jet fuel prices and resilient supply chain adjustments in the face of volatile trade policies, particularly between Asia and North America. While the Africa-Asia route still showed strength, experts say the broader cargo contraction highlights structural issues in intra-African trade, infrastructure inefficiencies, and exposure to commodity-driven markets.
The disparity between robust passenger growth and weakening cargo demand poses a strategic question for African carriers: how to balance capacity and investment across both segments of air transport. Air cargo, while representing less than 1pc of world trade by volume, accounts for over 33pc of global trade by value. This means African carriers must tread carefully to avoid lagging behind in the high-value, high yield freight segment.
Related Posts
 Isaiah Rwanyekiro: Wearing my Scars with Pride After Years of Battling Cancer
 Equity Bank Unveils Richard Byarugaba as it Targets Ugandans in Kenya with Cross-border Investment Proposition
 SITA’s New eWAS+ Electronic Flight Bag Integrates Weather and Flight Operations Data for Pilots
 United Opens new Dulles Concourse as it Expands International Network
 ICEA LION Urges Stronger Employee Protection as Insurer Backs HR Conference with UGX15m
 Stanbic Alerts Customers to Tighter OTC Transaction Limits Ahead of January 2027 Changes
Get business news delivered to you everyday
Latest News

Isaiah Rwanyekiro: Wearing my Scars with Pride After Years of Battling Cancer

Equity Bank Unveils Richard Byarugaba as it Targets Ugandans in Kenya with Cross-border Investment Proposition

SITA’s New eWAS+ Electronic Flight Bag Integrates Weather and Flight Operations Data for Pilots

United Opens new Dulles Concourse as it Expands International Network

ICEA LION Urges Stronger Employee Protection as Insurer Backs HR Conference with UGX15m

Nissan Patrol Marks 75 Years with Exclusive Anniversary Edition for Middle East Market

Financing Gap Hobbles Uganda’s Shift to Mercury-Free Gold Mining

Equity’s MSME Financing Helps Fill the Missing Middle in Uganda’s Economy

Commonwealth Study finds AI Could add USD900m to Uganda’s GDP by 2036

Equity Group Reports UGX3.1 trillion in Sustainability Investments